Affordability is the number one thing keeping buyers up at night right now. And with rates moving higher again lately, the instinct to wait is understandable.
The problem is that waiting may not help. Mortgage News Daily data shows rates have risen through much of this year, driven by a mix of factors: overseas instability, inflation readings, oil prices, and Federal Reserve decisions. Danielle Hale, Chief Economist at Realtor.com, put it plainly:
“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting.”
That’s not great news. But it’s not the whole picture. You can’t control where rates go from here. You can control several things that directly shape the rate you personally qualify for — and those levers are worth understanding before you decide to pause your search.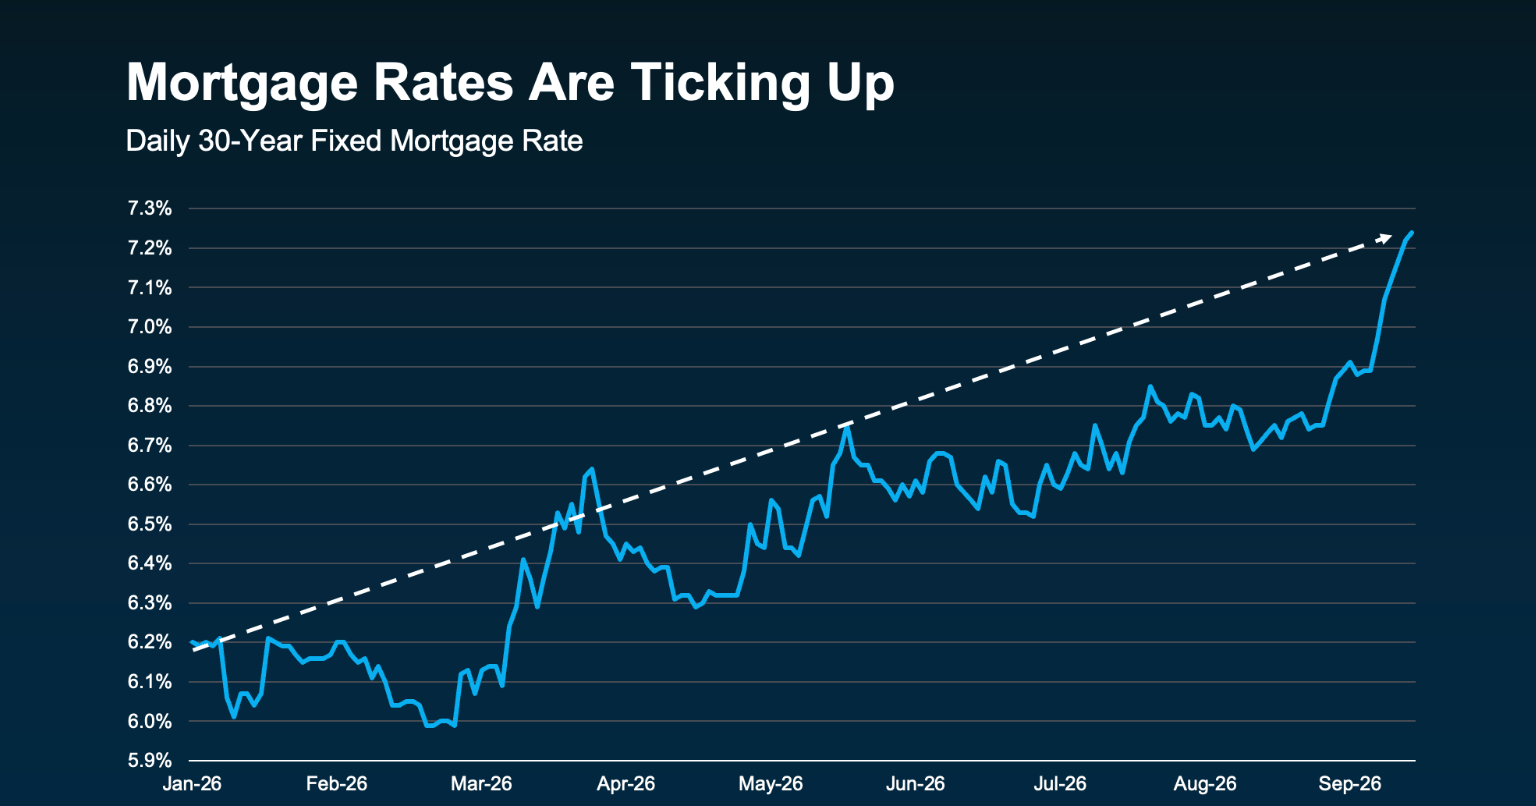
Graphic courtesy of Mortgage News Daily
1. Your Credit Score
This is the most direct lever you have. Lenders price risk, and your credit score is how they measure yours. Freddie Mac is straightforward about it:
“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.”
Even a modest improvement before you apply can translate into a meaningfully lower monthly payment over the life of a 30-year loan. If you’re not sure where your score stands or what’s pulling it down, a conversation with a trusted loan officer costs nothing and can tell you exactly where to focus.
2. Your Loan Structure
Not all loans are priced the same. Conventional, FHA, VA, and USDA loans each carry different rates and qualification requirements. Your loan term — 15, 20, or 30 years — changes both your payment and the total interest you pay. Fixed versus adjustable rate matters too. Adjustable loans typically start lower but carry future risk. Fixed loans cost a bit more upfront in exchange for certainty. As Bankrate explains:
“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.”
Talk to more than one lender, compare what each offers, and weigh the tradeoffs against your actual goals before committing.
3. The Type of Home You Buy
This one surprises people. Many homebuilders are currently buying down mortgage rates as an incentive to move inventory. According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes.
If a lower rate is a priority, it’s worth asking your agent which new construction communities in your area are currently offering this kind of incentive. The savings can be substantial.
What You Can Actually Do Today
Rates are going to do what they do. But your credit profile, your loan structure, and the home you choose are all within your control — and each one has a direct impact on the number you actually end up with.
Ready to figure out what rate you could realistically qualify for? The Vano Maurry Team works closely with trusted local lenders and can connect you with someone who will give you straight answers and a clear path forward for your budget. Reach out to us — we’re here to help you make sense of it.
Content courtesy of Keeping Current Matters. Graphic courtesy of Mortgage News Daily.